Missed the IFTA Q3 Deadline? What to Do Now
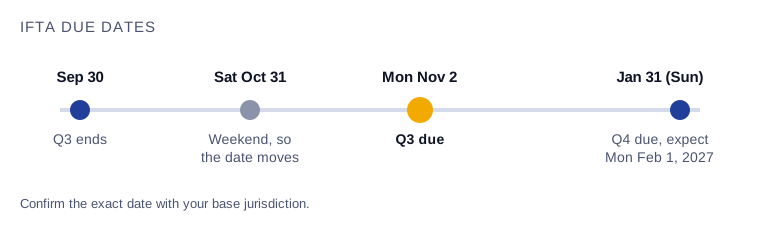
The third-quarter IFTA return covers July 1 through September 30 and is due October 31. In 2026 that date falls on a Saturday, so the due date moves to the next business day, Monday, November 2. If you have not filed yet, file now. Waiting makes the bill bigger.
What a late return costs
Under the IFTA Articles of Agreement, your base jurisdiction can charge a penalty for a late or missing return. The penalty is the greater of $50 or 10 percent of the tax due. Interest is charged on unpaid tax as well, and the exact rate and rules are set by your base jurisdiction. Some jurisdictions will waive the penalty for a good reason, but you have to ask.
A return is required even if you bought no fuel or drove no miles in the quarter. File a zero return rather than skipping it.
What to do today
- Collect the numbers. You need miles driven in each state and jurisdiction, total miles, and every fuel purchase with gallons, price, date and state.
- Work out your miles per gallon. Divide total miles by total gallons. A figure far from your normal usually means a missing receipt or a mistyped number.
- Calculate the tax by state. Use the current rates from the IFTA tax rate matrix, picking the quarter you are filing.
- File and pay through your base jurisdiction. Most have an online portal. Keep the confirmation.
- If you are past the date, file anyway and pay what you can. A late return with payment costs less than no return.
Keep this from happening next quarter
The usual cause of a late return is records scattered across receipts, a phone and a spreadsheet. Record each trip with its miles by state and each fuel purchase as it happens, and the return becomes a report instead of a project. Our IFTA quarter-end checklist walks through every step, and Trip Sheet Central builds the IFTA report from the trips and fuel you have already entered.
The fourth-quarter return, covering October 1 through December 31, is due January 31. In 2027 that falls on a Sunday, so expect Monday, February 1. Confirm with your base jurisdiction.